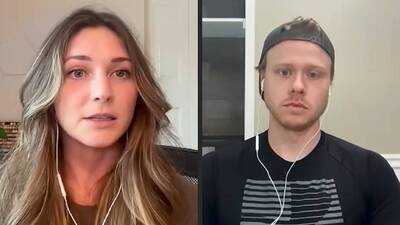
A Virginia couple who bought what they thought was their perfect home in their 20s are now considering selling it, despite having locked in a mortgage rate of just 2.7%. Chloe, 32, and her husband Jake, 30, purchased the four-bedroom property in late 2020, but what initially seemed like a dream investment has gradually turned into a source of financial and personal stress.
The couple recently opened up about their homeownership experience on the November 3 episode of personal finance author Ramit Sethi's podcast, I Will Teach You to Be Rich. Their story highlights how owning a house can bring unexpected responsibilities and expenses, even when buyers secure an unusually low mortgage rate.
The couple purchased the property from Jake's parents in late 2020, taking it in its existing condition without getting a home inspection. The four-bedroom Virginia house has an office, a swimming pool and sits on 1.5 acres of land.
According to Chloe, the property had once belonged to one of Jake's uncles, a multimillionaire whose grounds featured two koi ponds and a team of gardeners. However, much of the landscaping had been neglected by the time the couple took ownership.
At the time, they were paying $2,400 a month in rent. Jake believed that mortgage rates were unlikely to fall much further and felt that renting was money going to waste. The house was appraised at $595,000, considerably higher than their original budget of $500,000.
The mortgage was taken out in Jake's name alone. He explained that combining their credit scores would have put them below the 760 threshold they were aiming for, so Chloe was left off the loan.
“Honestly, signing that though, like I wanted to throw up,” Jake recalled, referring to the roughly half-million-dollar loan.
Their 2.7% mortgage comes with much higher ownership costsOne of the biggest reasons the couple has hesitated to sell is their exceptionally low mortgage rate. They locked in a 2.7% interest rate when the average 30-year fixed mortgage rate tracked by Freddie Mac was close to its record low of 2.65% in January 2021.
The contrast with today's borrowing environment is significant. Freddie Mac's November 12 survey put the average 30-year fixed mortgage rate at 7.11%. Data from the Federal Housing Finance Agency showed that only 19.2% of outstanding US mortgages had interest rates below 3% in the second quarter of 2026.
The couple's monthly mortgage payment, including escrow, has increased from $2,990 to $3,072. However, once maintenance and other homeownership expenses are factored in, Chloe and Jake estimate that the property costs them closer to $4,500 a month.
Yard work alone takes up approximately eight hours of their time on a typical weekend. For Chloe, who works as a software engineer, and Jake, a senior manager in an engineering department, maintaining the property has become an additional responsibility they no longer want.
“Everybody that we talk to is like, you know, homeownership is the dream,” Chloe told Sethi. “And I'm like, are we just dumb?”
An Airbnb plan, an expensive RV and other financial setbacks
The couple also admitted to making several financial decisions they now consider mistakes. Chloe referred to these ventures as their “schemes”.
Around two years ago, they took out an $80,000 home equity loan to renovate the property with the intention of turning it into an Airbnb rental. However, they had barely researched the area's rental demand before committing to the plan. Chloe later acknowledged that demand for short-term rentals in the area was soft.
They also purchased a 44-foot, eight-year-old recreational vehicle for $50,000, along with a new truck to tow it. However, getting the RV off their property proved so difficult that it never went on a trip. They eventually sold it two years later for between $30,000 and $32,000, taking a substantial loss.
At the time of their appearance on Sethi's podcast, they still had approximately $45,000 outstanding on the home equity loan. They were putting around $7,000 a month towards clearing that debt, which they need to settle before selling the house.
Ramit Sethi compares their financial future if they sell or stayDuring the podcast, Sethi examined the couple's finances and found that they were earning $30,166 a month before taxes, amounting to an annual household income of approximately $361,992.
They also had $304,000 in investments, $68,000 in savings and a combined net worth of approximately $692,000.
Jake has been in favour of selling the property and using the estimated $250,000 in home equity to invest in an S&P 500 index fund. His idea is to leave the money untouched and allow it to grow over the years, potentially securing a substantial part of their retirement savings while they are still young.
Chloe, however, has found it difficult to make a final decision. She has agreed with Jake after discussing the numbers, only to begin questioning the decision again shortly afterwards. One of her concerns is that the property's value could continue to rise, making selling it now a missed opportunity.
Sethi ran two possible retirement scenarios for the couple. If they kept the house and retired in 25 years, he estimated they could have approximately $4.8 million. If they sold the property and invested the equity, the figure could be closer to $6.2 million, although he noted that renting would likely eat into some of those gains.
“One way or another, both of these decisions will be fine,” Sethi told them, steering the conversation away from simply comparing financial projections and towards what they actually wanted from their lives.
The couple is reconsidering what homeownership means to themChloe had also considered renting out the property instead of selling it. However, she admitted that the yard had become a mess the last time they had tenants and that she would probably end up handling most of the responsibilities associated with managing renters.
Sethi cautioned them against allowing the property to dictate their decisions. He pointed out that if they no longer owned the house, they would also no longer have to worry about maintaining its well and septic system.
After months of going back and forth, Chloe appeared more open to the idea of moving on. She had previously spent around eight months debating whether selling the house would amount to another financial mistake.
“We can buy another house if we want to,” she said towards the end of the conversation. “We have the money.”
Contact to : xlf550402@gmail.com
Copyright © boyuanhulian 2020 - 2023. All Right Reserved.